contact us

Use the form on the right to contact us.

You can edit the text in this area, and change where the contact form on the right submits to, by entering edit mode using the modes on the bottom right.

Form Block
This form needs a storage option. Double-click here to edit this form, and tell us where to save form submissions in the Storage tab. Learn more
         

123 Street Avenue, City Town, 99999

(123) 555-6789

email@address.com


You can set your address, phone number, email and site description in the settings tab.
Link to read me page with more information.

Blog

Accredited Investor Verification in 2026: What "Reasonable Steps" Under Rule 506(c) Actually Requires

VerifyInvestor.com
Most of the regulatory energy in private capital markets right now is pointed at one question: who gets in. Very little of it is pointed at the question issuers have to answer at closing, which is how you prove the person wiring money belongs in the deal. Those are different problems, and conflating them is how otherwise careful offerings lose their exemption.

What the SEC Is Actually Doing Right Now

The Commission's Spring 2026 regulatory agenda, published July 7, 2026, carries two items that matter to anyone raising under Regulation D.

The first, "Updating the Exempt Offering Pathways" (RIN 3235-AN42), contemplates simplifying the pathways for raising private capital, and expressly includes potential amendments to the accredited investor definition so that more investors can participate. The second, "Enhancing Retail Exposure to Private Markets" (RIN 3235-AN59), would amend rules under the Investment Advisers Act and the Investment Company Act to let retail investors reach private market assets through registered funds, in part by permitting advisers to charge performance fees beyond today's "qualified client" population. Reporting in early September 2026 indicated the Commission had sent a proposal along these lines to the White House Office of Management and Budget for review.

Two things follow. This is direction, not law: an agenda item is a statement of intent, and a proposal at OMB is a draft that has not been published, commented on, or voted. And none of it touches Rule 506(c)'s verification condition. The proposals aim at eligibility and at fund structures. The obligation to take reasonable steps to verify that your purchasers are who they say they are sits where it has sat since 2013.

The Thresholds That Have Not Moved

The individual accredited investor tests have never been indexed to inflation. Annual income over $200,000 individually, or $300,000 jointly with a spouse or spousal equivalent, in each of the two most recent years with a reasonable expectation of the same in the current year. Or net worth over $1 million, individually or jointly, excluding the primary residence. The Dodd-Frank Act requires the SEC to review the definition every four years, and staff have done so, most recently in a December 2023 report. Review is not amendment.

The 2020 amendments added paths unrelated to wealth: holders of a Series 7, Series 65, or Series 82 license in good standing; "knowledgeable employees" of a private fund investing in that fund or its affiliates; family offices with more than $5 million in assets under management and their family clients; and entities owning more than $5 million in investments. These are underused, and easier to verify than an income or net worth test, because license status is a public record.

Rule 506(c) in Plain Terms

Regulation D's Rule 506(b), the older and still more common path, lets an issuer raise an unlimited amount from accredited investors and up to 35 sophisticated non accredited investors, but forbids general solicitation and lets the issuer rely on investor self certification.

Rule 506(c) trades one constraint for another. You may advertise the offering publicly: a website, a webinar, a conference stage, a LinkedIn post, a demo day. In exchange, every purchaser must actually be an accredited investor, and the issuer must take reasonable steps to verify that status. Form D is still due within 15 days of the first sale, and the bad actor disqualification provisions still apply.

The trade is usually worth it for anyone whose deal flow depends on being findable. The risk is that the two conditions are linked. If you solicited generally and a purchaser turns out not to be accredited, 506(b) is not available as a fallback, because you already advertised. The exemption fails, and rescission rights and state law exposure follow.

What "Reasonable Steps to Verify" Means

The standard is principles based: an objective determination by the issuer, in the context of the particular facts and circumstances of each purchaser and transaction. Relevant factors include the type of accredited investor the purchaser claims to be, the information the issuer already has about that purchaser, and the nature of the offering, including how investors were solicited and the terms on offer.

Rule 506(c)(2)(ii) then provides a non exclusive list of methods that are deemed to satisfy the standard for natural persons:

•      Income: review IRS forms reporting income for the two most recent years (W-2, 1099, Schedule K-1, Form 1040), plus a written representation of a reasonable expectation of reaching the required level in the current year.

•      Net worth: review documentation dated within the prior three months, such as bank or brokerage statements and appraisals for assets, and a consumer report from a nationwide agency for liabilities, plus a written representation that all liabilities have been disclosed.

•      Third-party confirmation: written confirmation from a registered broker-dealer, an SEC registered investment adviser, a licensed attorney, or a certified public accountant that the person has taken reasonable steps to verify accredited status within the prior three months.

•      Existing investors: a certification from a person who invested in the issuer's prior 506(b) offering as an accredited investor before Rule 506(c) took effect and remains an investor.

These are safe harbors, not the whole universe. You can satisfy the standard another way. You just carry the burden of showing that you did.

The March 2025 Minimum Investment Pathway

On March 12, 2025, the Division of Corporation Finance issued a no-action letter to Latham & Watkins LLP and published two related Compliance and Disclosure Interpretations, Securities Act Rules Questions 256.35 and 256.36. Together they describe a verification approach built on investment size rather than document review.

Where a natural person invests at least $200,000, or an entity at least $1 million, and the issuer obtains written representations that the purchaser is accredited and that the minimum investment is not financed in whole or in part by any third party for the specific purpose of making that investment, the staff indicated it would not object to treating that as reasonable steps, provided the issuer has no actual knowledge of facts indicating otherwise. Binding capital commitments subject to later capital calls count toward the minimum. For entities owned by fewer than five natural persons, a $200,000 per equity owner test is available.

This is genuinely useful for funds with high minimums. It is also frequently overstated. Three cautions:

It is staff guidance, not a rule change. The text of Rule 506(c) is identical today to what it was before the letter. No-action relief reflects the staff's enforcement posture. It does not bind the Commission, and it does not resolve private litigation or a state regulator's view.

The conditions are doing real work. "No actual knowledge of contrary facts" is not a passive standard. If your own marketing materials, subscription documents, or prior correspondence contain a red flag, the pathway closes.

It fits a narrow band of offerings. A syndication with a $50,000 minimum, a startup taking $25,000 checks, a Reg D real estate deal with a broad investor base: none of these qualify. For most issuers using general solicitation, verification still means evidence about the individual.

Why Self Certification Alone Still Fails

A checkbox questionnaire is sufficient under Rule 506(b). Under Rule 506(c), standing alone, it is the single most common defect in an offering file. The rule requires steps to verify, and asking someone to confirm the thing you are supposed to be confirming is not a step. Staff guidance has been consistent that an issuer cannot rely on a short form accreditation questionnaire alone and must have, and actually use, enough information to evaluate the claim.

Three Thresholds That Get Confused

Issuers routinely treat "accredited" as the only gate. Depending on the vehicle, it is one of three, and they stack.

Accredited investor (Rule 501(a)) governs who may buy in a Reg D private placement. The tests are above.

Qualified client (Advisers Act Rule 205-3) governs who an adviser may charge performance based compensation. These thresholds adjust for inflation every five years. By order dated April 28, 2026, effective June 29, 2026, they rose to $1.4 million in assets under management with the adviser, or $2.7 million in net worth, up from $1.1 million and $2.2 million. Any fund charging carried interest to individuals should re-paper its qualification process against the new numbers.

Qualified purchaser (Investment Company Act Section 2(a)(51)) governs eligibility for 3(c)(7) funds, which can accept an unlimited number of investors so long as all of them qualify. A natural person needs $5 million in investments; a person managing accounts on a discretionary basis for other qualified purchasers needs $25 million.

A single investor in a single fund can need to clear all three, and they are tested on different measures at different moments.

AML/KYC Sits Alongside, Not Inside, Verification

Accredited investor verification answers eligibility. It does not answer who the investor is, whether they are sanctioned, or where the money came from. Those are separate screens, and they do not go away because a federal timeline moved.

FinCEN's anti-money laundering program and suspicious activity reporting rule for registered investment advisers and exempt reporting advisers, originally effective January 1, 2026, was postponed by final rule at the end of December 2025 to January 1, 2028. The compliance deadline moved. The expectations of institutional limited partners, banking partners, and transfer agents did not. Most private funds run AML/KYC screening today because their counterparties require it, not because FinCEN does yet.

Enforcement makes the same point from the other side: in August 2026 the Commission charged 38 entities that had manufactured false filings to appear to be legitimate U.S. advisers while soliciting retail investors.

The Real Deliverable Is the File

If your exemption is ever questioned, by a plaintiff's lawyer in a down round, by a state regulator, or in diligence on your next raise, nobody will ask what your process was. They will ask to see the file.

A defensible file is contemporaneous and complete: it identifies which accredited investor category each purchaser relied on, records what evidence supported it and when that evidence was dated, shows who made the determination, and is retained for the life of the investment. Verification is also point in time. A determination is generally treated as good for 90 days, so an investor returning for a follow on close needs a fresh look.

This is the work issuers underestimate, and it is why third-party verification exists. An outside provider keeps investors' tax returns, brokerage statements, and credit reports out of the issuer's hands entirely, which reduces both friction and data liability, and it produces a standardized accredited investor certificate that a regulator or acquirer can read without reconstructing your judgment from a folder of PDFs.

A Practical Next Step

Before your next 506(c) close, work through five questions. Which accredited investor category is each purchaser relying on, and is it written down? Does the supporting evidence meet the rule's recency requirements? If you are using the minimum investment pathway, do your subscription documents actually track the March 2025 conditions, including the third-party financing representation? Does the vehicle also require qualified client or qualified purchaser status, and are you testing for it separately? And is AML/KYC screening happening at all, whatever the FinCEN calendar says? If the answers are uneven, that is the gap worth closing first.

VerifyInvestor.com has handled accredited investor verification for Rule 506(c) offerings since general solicitation became available, with every verification reviewed by a licensed attorney rather than resolved by an automated document scan. The platform also covers qualified purchaser and qualified client verification, AML/KYC screening, and On-ChainPass, which issues verification results as tokenized, reusable investor credentials for issuers working with digital securities. Investors upload documentation directly to the platform rather than to the issuer, and verifications are typically completed within one to two business days. VerifyInvestor.com is majority owned by tZERO Group.

Private markets look likely to get wider. The gate will stay, and it will be inspected more often, not less.
There is More than $4 Trillion Waiting to Be Invested

VerifyInvestor.com

There is more than $4 trillion waiting to be invested.

So why do so many legitimate companies still fail to raise capital?

Those two facts cannot both describe a healthy market. Trillions of committed capital on one side. Real businesses on the other. Yet the two routinely miss each other. Everyone involved has a theory about why, and all the theories are wrong in the same direction.

In most markets, that’s the point where economists start to feel uneasy.

Exhibit A: The money

Private equity firms today sit on roughly $2.5 trillion of committed capital. Add venture capital, private credit, infrastructure, and real assets, and global dry powder clears $4.6 trillion, according to PitchBook. This is not hypothetical money in someone’s aspirational spreadsheet. Committees have met. Mandates have been drafted. Fees are being paid whether the money moves or not — which, incidentally, is the one part of this system that never experiences friction.

The money has done everything except its actual job.

Invest.

And yet, week after week, business owners, independent sponsors, and advisers repeat the same sentence:

“There’s just no capital out there.”

If that were true, it would be depressing. Because it’s false, it’s more interesting.

The Federal Reserve’s 2025 Small Business Credit Survey has the receipts: only 46 percent of applicants got the full amount they asked for; 22 percent got nothing; businesses applying for SBA‑backed loans were denied 45 percent of the time — more than double the rate across all loan types. Black‑owned businesses were denied 39 percent of the time, against 18 percent for white‑owned firms with comparable credit profiles.

And that’s just the people who applied. The Fed keeps a separate tally for “discouraged borrowers” — businesses that needed money and didn’t bother, because they had already decided the answer was no. Nobody knows how big that group is. Declining to show up doesn’t generate a data point.

So on paper, there is too much capital. On the ground, there is never enough. Between those two realities lies the real story.

Exhibit B: The scam

Consider one small case study.

A friend of mine recently lost just over $1 million.

Before you picture wiring money to a Nigerian prince, revise the scene. This didn’t happen in a spam folder. It happened in meeting rooms.

He’s an experienced independent sponsor. Years of deals. The sort of person compliance departments like to call “a sophisticated party” — which, it turns out, is not the same as an observant one.

A private investment fund from Switzerland expressed interest in a nine‑figure transaction. Its executives flew to the site. They toured the facilities. They questioned management. They reviewed financials. They negotiated terms and produced documentation that would have looked perfectly normal in any data room.

Nothing about this resembled a cartoon scam. No typos. No improbable urgency. No “dear sir” emails. Just polite professionals who spoke the right language and asked the right questions.

Eventually, they asked that certain transaction‑related payments be routed through digital wallets. Somewhere between those wallets and the devices that controlled them, $1 million disappeared.

The fund, the executives, the transaction — none of it had ever existed. Everything was counterfeit except the loss.

The obvious response is anger. A more useful one is unease.

He is one data point inside the $8.6 billion the FBI logged in investment fraud last year, the single largest loss category it tracks, inside a system where total reported losses hit $20.9 billion — a 26 percent jump in a single year. Older Americans lost $7.7 billion of that, up 59 percent.

The number climbs every year. So does the number of task forces formed to lower it.

Zoom out, and the fraud starts to look less like a freak event and more like a clue.

Imagine air traffic control designed this way

Change industries for a moment.

Imagine if commercial aviation worked like private capital. Thousands of aircraft. Thousands of airports. Plenty of fuel, plenty of passengers. But no radar. No transponders. No shared identity system. Pilots would spend their careers re‑introducing themselves to one another before takeoff. Every flight plan would begin with a warm introduction. Every safe landing would feel like a triumph of networking.

We wouldn’t call that infrastructure. We’d ground the fleet.

Yet that’s roughly how private markets still behave. There is no global, credible way to answer three basic questions at scale:

Who is this?
Can they do what they claim?
What’s their history?

Private capital likes to think of itself as sophisticated. For an industry that allocates trillions, it’s remarkably bad at answering the first question every transaction depends on: Who are you?

Markets confess their weaknesses

Markets are surprisingly honest.

They confess their weaknesses in the industries they build to route around them.

If thousands of conferences exist, the market can’t efficiently connect participants. If placement agents thrive, the market can’t efficiently transfer confidence. If investor databases proliferate, the market can’t efficiently identify who is who. If verification and diligence firms multiply — and they have; there is now an entire sub‑industry billing by the hour to confirm what a functioning market should already know — then legitimacy has never been standardized.

Markets don’t build billion‑dollar industries around solved problems. They build them around expensive uncertainty.

For years I described this as a trust problem. It isn’t. Or at least, trust isn’t the primitive.

Private markets still run on social discovery — dinners, reputations, who‑knows‑whom — standing in for the systems every other mature market eventually builds. Trust is personal. Social discovery doesn’t scale.

The result is an economy that keeps trying to solve an infrastructure failure with more relationships.

From indexing to social discovery

The internet didn’t create information. It made information findable.

Amazon didn’t invent products. It made them searchable.

LinkedIn didn’t create professionals. It made them findable without an introduction.

Bloomberg didn’t create securities. It made them visible.

Every great market expansion begins with the same move: reduce the cost of discovery.

Then, private capital.

Private market participants remain largely socially discovered — found at the speed of a calendar instead of the speed of a query.

Conferences are social discovery. Placement agents are social discovery. Investor databases are social discovery. Spreadsheets titled “Top 200 Family Offices” are social discovery. So is roughly 200,000 companies’ worth of the U.S. middle market — companies generating $10 trillion in revenue and employing 48 million people, according to the National Center for the Middle Market — still getting found mostly by who happened to sit next to whom at a conference dinner.

It’s 2026 and the state of the art is still a warm introduction.

The visible losses, and the invisible ones

Regulators can at least count a fraction of the price. The FBI’s $8.6 billion. The average private equity holding period stretching to nearly seven years before exit, almost double the roughly four years typical in 2007 — because sponsors can’t move capital in or out at the pace the diligence and trust‑rebuilding now demands. Bain put the resulting backlog of unsold, PE‑owned companies at roughly 32,000 as of 2026, worth an estimated $3.8 trillion.

Those are the harsh numbers. They’re also the easy part, because somebody, somewhere, was willing to publish them.

The invisible losses are almost certainly larger, and nobody has built the index that would let us count them.

We don’t know how many profitable companies quietly shelved expansion because financing never materialized. We don’t know how many acquisitions collapsed after months of diligence simply because the right capital never found them. We don’t know how many of the world’s estimated 8,030 family offices, managing a combined $5.5 trillion, walked away from real opportunities because verifying them demanded too much bespoke detective work. We don’t know how many founders quietly concluded that outcomes depend more on introductions than fundamentals, and looked elsewhere.

We don’t know how many jobs were never created. How many factories were never built. How many technologies arrived years late, or not at all.

None of that appears in a fraud statistic, because none of it was stolen — it just never happened. Stolen money at least existed, then got taken. That’s a story with a beginning. Capital that never finds a credible opportunity never even gets a story.

Fraud as an arbitrage

Seen through this lens, even fraud looks different.

The comforting story is that fraud is a moral aberration — a few bad actors, a few weak controls, solvable with a stronger onboarding form.

The less comforting story is that fraudsters aren’t creating uncertainty. They’re arbitraging it.

They profit from the fact that in one of the most sophisticated financial systems on earth, a well‑constructed imitation can move through the pipes almost as easily as a genuine counterparty — sometimes more easily, because genuine counterparties get asked more questions.

That’s exactly what you’d expect from a market that still discovers people socially instead of systematically: plenty of noise, plenty of room for mimicry, and a steady, quiet flow of profitable misunderstandings that never make the evening news because nobody involved wants to explain how a “sophisticated party” got taken for seven figures by a well‑dressed PDF.

Fraud isn’t the deepest failure here. It’s the most visible trade available on a more basic flaw — and it’s the only part of the flaw anyone is currently keeping score on.

What history might notice

Put the exhibits together.

Exhibit A: $2.5 trillion in private equity dry powder, $4.6 trillion once you count the rest.

Exhibit B: $8.6 billion in measurable investment fraud, out of $20.9 billion in total fraud losses, up 26 percent in a year.

Exhibit C: a scam sophisticated enough to fool a professional who does this for a living, on a nine‑figure deal, with site visits and a full data room.

Exhibit D: an entire ecosystem of conferences, placement agents, databases, and diligence firms — built, correctly, to route around a market that can’t answer “who is this” on its own.

Exhibit E: 200,000 legitimate middle‑market companies and 8,030 family offices, all supposedly looking for each other, still finding each other mostly by accident.

At some point, it gets hard to maintain the polite fiction that this is a fundraising challenge.

We often judge markets by the products they create. Judge them instead by the industries they need to compensate for what they cannot do. Markets don’t build billion‑dollar industries around solved problems.

Every mature market eventually replaces relationships with infrastructure — not because relationships stop mattering, but because they stop being the prerequisite for participation.

We indexed books.

We indexed companies.

We indexed people.

We even indexed the internet itself.

Yet in the one market where knowing who you’re dealing with is the entire game, we never quite indexed legitimacy — a strange gap to leave open in the one corner of the economy where legitimacy is the entire product.

Every market eventually solves its most expensive uncertainty.

Private capital hasn’t solved this one yet.

Which leaves one surprisingly primitive question at the center of a multi‑trillion‑dollar market:

Who, exactly, is on the other side of this transaction?


VerifyInvestor.com: The Quiet Compliance Engine Behind Private-Market Investing

VerifyInvestor.com

Every time a private company raises capital from the public, an invisible question has to be answered before a single dollar changes hands: is this investor actually allowed to invest? For more than a decade, VerifyInvestor.com has built its business on answering that question quickly, cleanly, and in a way that holds up when regulators come knocking.

A company born from a rule change

VerifyInvestor.com traces its origins to a pivotal shift in U.S. securities law. When the JOBS Act took effect, a new exemption known as Reg D Rule 506(c) allowed issuers to publicly advertise, or "generally solicit," private investment offerings for the first time. The tradeoff was a new obligation: issuers could no longer simply take an investor's word for it. They now had to take reasonable steps to verify that each participant was genuinely accredited.

That single requirement created an entire category of compliance work overnight. An investor typically qualifies as accredited by meeting income thresholds of $200,000 individually or $300,000 with a spouse, or by holding a net worth above $1 million excluding their primary residence. (The definition has since broadened to recognize certain professional licenses and financial sophistication.) Confirming those facts, reviewing sensitive financial documents, and producing an audit-ready record is exactly the kind of task most issuers, sponsors, and platforms would rather not build in-house.

Co-founded by brothers JL Law and JT Law, VerifyInvestor.com was one of the earliest movers to industrialize that process. Rather than leaving verification to ad-hoc letters from lawyers and accountants, the company created a streamlined online service that could confirm accredited status reliably and at scale, giving issuers a defensible compliance trail and giving investors a confidential, standardized way to prove their eligibility once rather than repeatedly.

Joining the TZERO ecosystem

In early 2018, the company reached an inflection point when tZERO, a financial-technology firm focused on the future of capital markets, acquired a majority stake. VerifyInvestor.com became a majority-owned subsidiary while continuing to operate its verification platform.

The acquisition was more than a change of ownership. tZERO is backed by significant institutional investors, including interests tied to the New York Stock Exchange's parent, and has spent years building regulated infrastructure for digital securities, ultimately becoming one of only a small number of firms approved to provide compliant digital-securities custody in the United States. Folding investor verification into that ecosystem gave VerifyInvestor.com a strategic role: it became a foundational compliance layer beneath tZERO's broader ambitions in tokenization and private-market liquidity.

From a single product to a compliance suite

What began as accredited-investor verification has grown into a full onboarding-compliance offering. The core accreditation product remains the flagship, but issuers today face a tangle of obligations that rarely stop at accreditation alone. Historically, that forced them to stitch together multiple vendors, each handling one slice of the process.

VerifyInvestor.com set out to collapse that fragmentation. In 2024, it launched an anti-money-laundering and know-your-customer screening service, adding identity verification, biometric liveness and face-match checks, sanctions and AML screening, and ongoing monitoring for emerging risk. The result positioned the company as a single destination for the two compliance functions issuers most often need together: confirming who an investor is and confirming that they qualify.

Around the flagship product sits a wider menu: qualified purchaser and qualified client verifications for offerings with higher sophistication thresholds, fully customizable verification workflows that issuers can tailor to their own requirements, and true-and-correct certification of critical documents such as government IDs, passports, and proof of address. The through-line is consistency: one provider, one standard, one record that stands up under audit.

Betting on the on-chain future

The company's most forward-looking move arrived in late 2025 with On-ChainPass, a tokenized investor passport. Built on Soulbound Tokens, non-transferable blockchain credentials tied to a specific holder, On-ChainPass lets an investor verify their identity and accreditation once and then carry that verified status across multiple offerings without repeatedly exposing sensitive personal information.

The idea addresses one of the most persistent frustrations in private markets: investors re-submitting the same documents to every new deal, and issuers re-running the same checks. By turning a verified credential into a portable, privacy-preserving token, On-ChainPass aims to bring compliant identity and eligibility directly into decentralized finance and digital-securities workflows, where verification has traditionally been a stumbling block. It is a natural expression of the company's place inside tZERO's digital-securities infrastructure, extending trusted verification onto the rails where the next generation of assets is being built.

Why it matters

Compliance rarely makes headlines, but it determines whether capital can move at all. VerifyInvestor.com occupies an unglamorous yet essential position in the private-market stack: the checkpoint that lets legitimate offerings reach legitimate investors while keeping fraud, ineligible participants, and regulatory risk out. Its clients have used that verification trail to navigate audits and investigations, a reminder that the real product is not a checkbox but defensibility.

As private markets expand and as tokenization pushes more of finance on-chain, the demand for fast, reliable, and portable proof of who an investor is, and what they're allowed to do, only grows. Having spent a decade turning a regulatory requirement into dependable infrastructure, VerifyInvestor.com is positioned to remain the quiet engine making that participation possible.

You asked about digital assets. Let's talk. [Live Q&A]

VerifyInvestor.com

Hi Accredited Investors from VerifyInvestor.com,

In a recent survey of our verified accredited investor community, a clear theme came through: many of you want to understand what's actually happening with digital assets and tokenization, beyond the headlines.

So we're hosting a live webinar with Q+A built around exactly that.

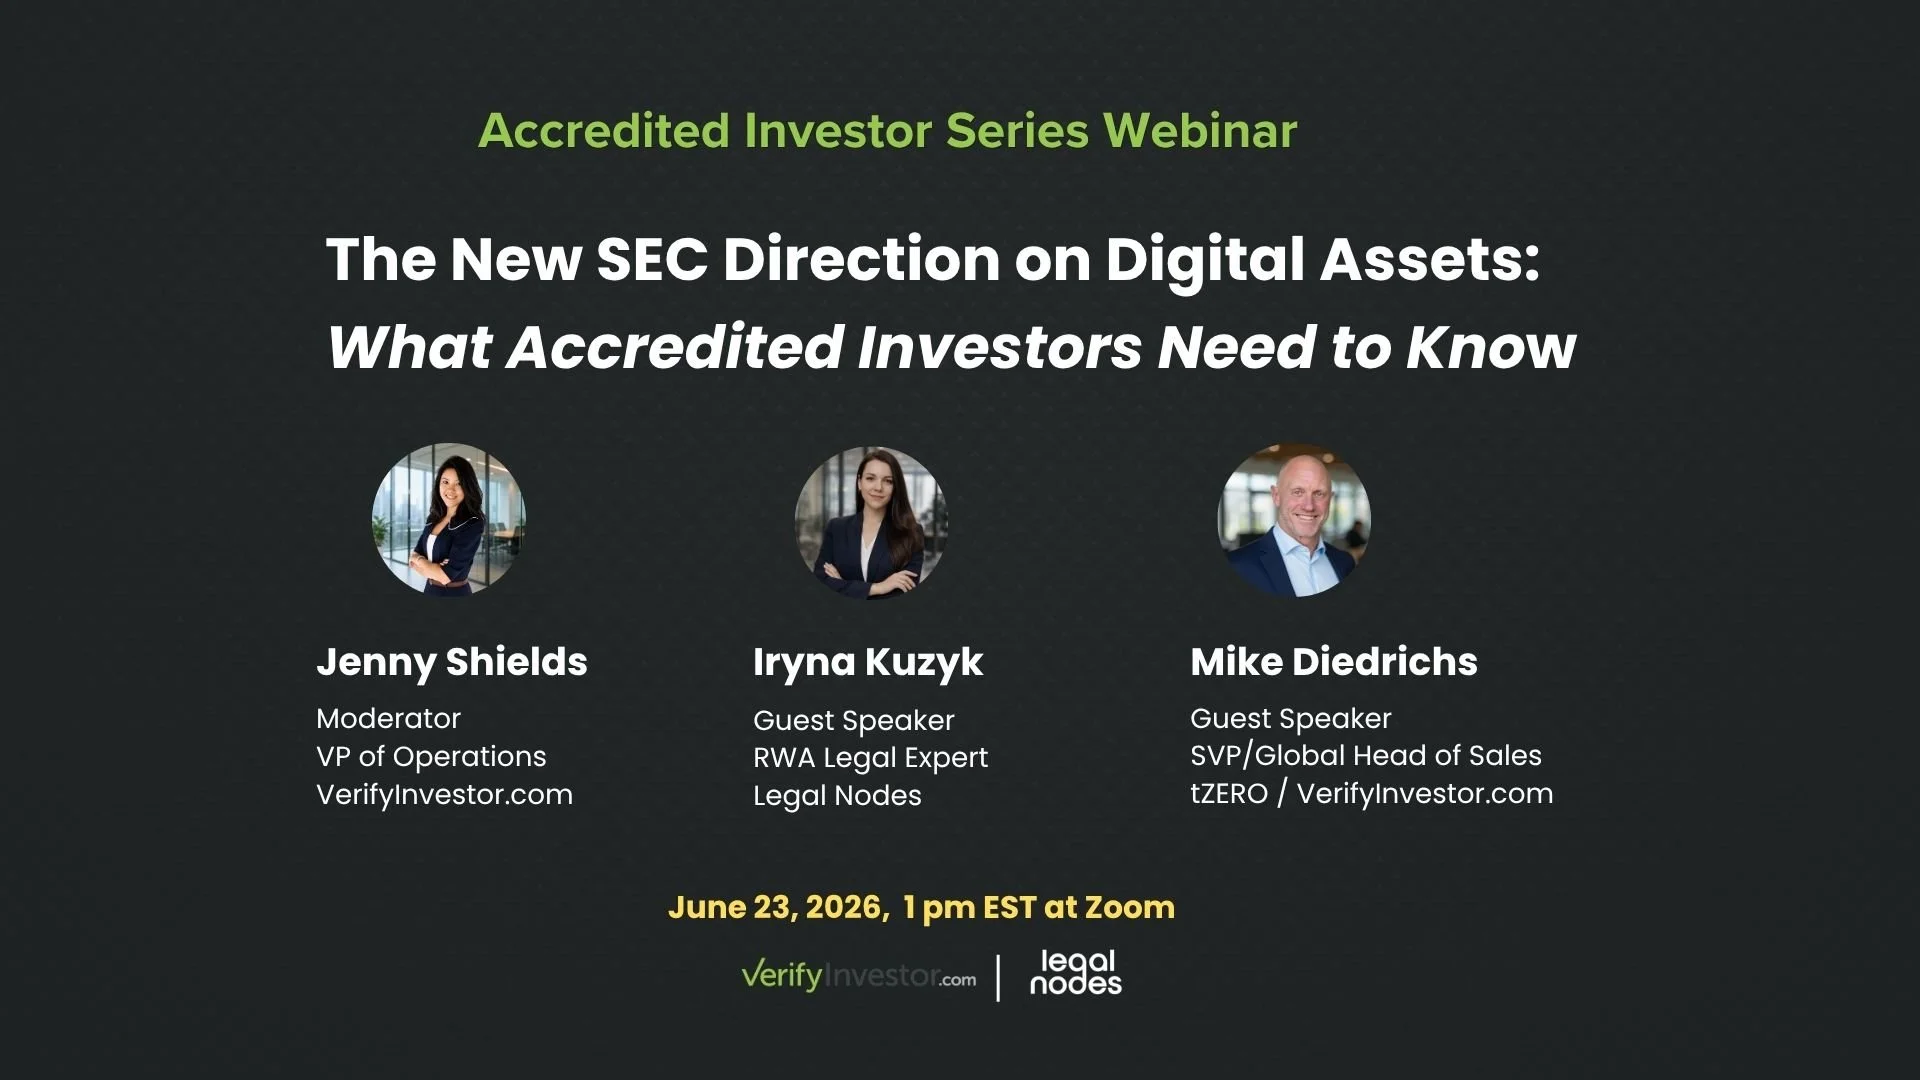
The New SEC Direction on Digital Assets: What Accredited Investors Need to Know 

June 23, 1 p.m. EST via Zoom live webinar

Over recent months, the SEC has issued formal guidance on tokenized securities, addressed structures involving tokenized money market funds, and, alongside the CFTC, released a digital asset taxonomy framework. We'll unpack what's changed, what it means for private market participants, and where this is likely heading.

Moderated by Jenny Shields, VP of Operations at VerifyInvestor.com, with:

  • Iryna Kuzyk, tokenization expert at Legal Nodes, on the legal and regulatory structuring behind tokenized securities

  • Mike Diedrichs, SVP / Global Head of Sales at tZERO Group / VerifyInvestor.com, on institutional infrastructure for digital securities

We'll cover the topics that came up most in your survey responses, how tokenization fits within existing securities law, which real-world assets are drawing institutional attention, the legal structures behind these offerings, and the risks worth scrutinizing before participating.

A live audience Q&A is included. Bring your questions; this is your chance to ask the experts directly. You can also submit a question in advance when you register.

[Reserve My Spot →]

We're keeping this exclusive to our community of verified accredited investors.

VerifyInvestor.com

This session is for general educational and informational purposes only and does not constitute legal, financial, investment, tax, or corporate advice. Please consult an independent professional before making any investment, structuring, or compliance decisions.


SEC Explores Modernizing RMBS Regulations to Boost Housing Affordability

VerifyInvestor.com

Few would dispute that the United States is currently facing a housing crisis. A combination of factors,  including housing shortages, soaring home prices, the lasting effects of the pandemic, rising property taxes, high interest rates, proposed tariffs, and more, has resulted in what has now become an acute housing crisis. 

Unaffordable housing and the lack of adequate housing supply directly affect the health of the U.S. economy. It affects labor markets and the country’s overall productivity. High housing costs leave consumers with less money to spend and make it harder or impossible for workers to move to areas with better job opportunities.

Read More

Navigating Secondary Transactions: Opportunities and Pitfalls for Private Market Issuers

VerifyInvestor.com

For securities, there are two types of markets: the primary market and the secondary market.

The primary market is the place where securities are first issued by various companies or the government, and are then sold directly to investors, to raise capital for growth or to support various company projects. Only new or previously unissued securities are sold in the primary market. 

The secondary market, on the other hand, is where investors and traders go to buy and sell securities among themselves. These are securities that were issued and purchased in the primary market. However, instead of selling their interests back to the company that issued them (i.e., the issuer), secondary markets allow investors and traders to sell their securities among themselves. Two of the most recognizable secondary markets are national exchanges: the New York Stock Exchange and the Nasdaq.

Read More

A Practical Guide to Blue Sky Law Compliance

VerifyInvestor.com

When it comes to securities law compliance, most discussions regarding private equity and issuers tend to focus only on the federal rules and regulations. The bulk of articles examining securities law issues or compliance speak only to the Securities and Exchange Commission’s (SEC) approach and enforcement actions. However, this tells only half the securities law story. For issuers and private equity investors, the other half of the compliance story lies with the states. State “blue sky laws” may not get a lot of press, but they play an important role in compliance. Obeying state “blue sky laws” is every bit as critical as complying with the Securities and Exchange Act of 1934 (“Securities Act”).

Read More

Securities Law Implications of Private Placement Memoranda in Regulation D Offerings

VerifyInvestor.com

When companies (whether public or private) want to raise capital to start their business or fund operations, improvements, or expansion of the business, they often turn to offering and selling securities to investors to raise the money they need. 

While capital raising is never easy, securities are one of the most popular ways for startups and established companies alike to raise money from investors. But before securities can be offered or sold, they must be registered with the Securities and Exchange Commission (SEC) unless they come within a legal exemption. SEC registration is a laborious, complicated, and expensive process. Which is why most companies look for an exemption from registration under the Securities and Exchange Act, such as Section 4(a)(2) or Regulation D (“Reg. D”). Not having to register securities can save a company a significant amount of time and expense. 

Exempt security offerings are referred to as “private placements.”

Read More

Legal Overview of EB-5 Immigrant Investor Program Offerings and SEC Compliance

VerifyInvestor.com

The EB-5 Investment Program — What Is it?

The U.S. market offers the largest consumer market on earth and boasts the highest global household expenditure. On top of that, the U.S. has one of the most open markets and best investment climates in the world. So it’s no wonder that the U.S. is the top destination for foreign business investors.

Foreign nationals who want to live and work in the United States have a fast track to permanent residence if they are also investors. In 1990, Congress established the “EB-5 Immigrant Investor Program” (referred to herein as “EB-5,” the “EB-5 Program,” or “the Program”) to allow foreign investors and their families (spouse and unmarried children under the age of 21) to obtain permanent residency (a green card). The EB-5 Program — named for the visa received (“employment-based fifth preference”) — can be the fastest way to become a permanent U.S. resident.  

If, that is, you can qualify for the Program.

Read More